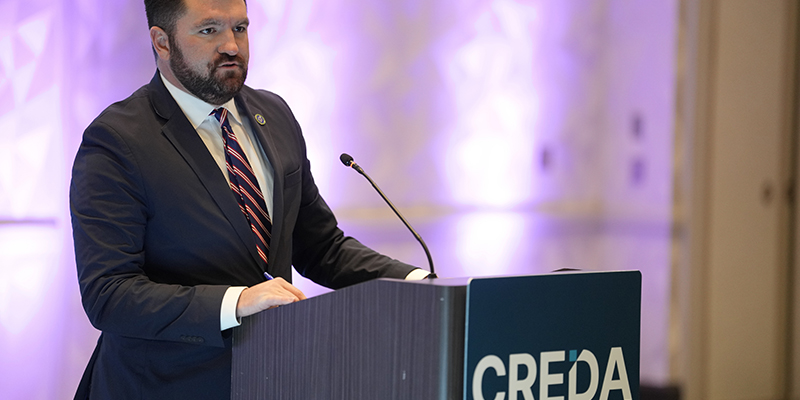
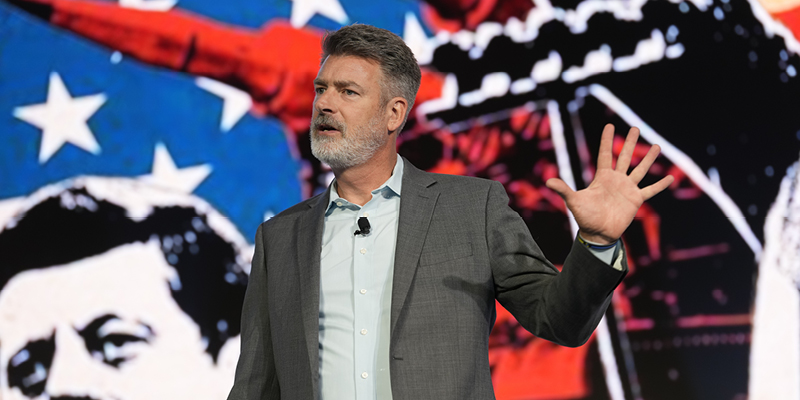
Geopolitical strategist Peter Zeihan delivered the breakfast keynote at the CREDA Conference in Denver, a wide-ranging talk on the end of globalization, shifting demographics and global security.
You had to be in the room to hear all of it; below, a few of his key insights into the state of U.S. industrial construction, the limits of the nation’s power grid and the future of data center demand.
Industrial Plant: A Stalled Build-out
If attendees track only one statistic, Zeihan said, it should be total construction spending on manufacturing facilities – “shovels going into the ground.”
He attributed the recent surge in that spending primarily to private enterprise rather than federal incentives, noting that the Inflation Reduction Act and CHIPS Act together accounted for less than 20% of the total. “I would interpret the surge as American private enterprise realizing that we need to double the size of the industrial plant to prepare for the end of China and globalization,” he said.
That momentum has reversed. Zeihan pointed to tariff uncertainty – he cited the 10,000th tariff change since January of last year – as a deterrent to long-term planning. The result, he said, is “the biggest decline in industrial construction spending in modern history at a time that this number really needs to be at least twice what it is already.” He added that about 40% of the spending that remains is for data centers.
Power: The Grid is a Local Constraint
Zeihan described a second obstacle: the nation’s high-voltage transmission network. High-capacity transmission lines are concentrated in Appalachia, a legacy from the 1960s, 1970s and early 1980s when these were established to move power from coal country to nearby population centers rather than ship the coal itself.
“If we need to double the size of the industrial plant, that means we need at least 50% more electricity,” he said, adding: “That assumes we don’t build another data center.”
Outside the areas served by high-capacity lines, power generation and manufacturing generally must be located close together. “It’s very rare in the United States to get your electricity from more than 50 miles away from where you are,” Zeihan said.
Asked what one federal policy change would most accelerate domestic industrial construction, he pointed first to congressional action to make it easier to ship electricity across state borders. “Until you get that, we’re all kind of stuck struggling on our own,” he said. He also called for changes to the Jones Act, which requires that cargo moved between U.S. ports must travel on American-built, -owned and -crewed ships, which has pushed freight from waterways to trucks.
Data Centers: Build Now, Get Paid Up Front
When asked which geopolitical shift the commercial real estate industry is most underestimating, Zeihan answered: “The end of data centers.”
He clarified that data centers will remain essential for the internet, computing and other existing uses. His concern is the AI-driven expansion, which depends on high-end semiconductors produced through one of the most complex supply chains ever built – more than 100,000 distinct steps, 30,000 inputs and 9,000 companies across roughly 50 countries. In Zeihan’s view, that supply chain cannot survive the breakdown of globalization, and rebuilding it could take at least 20 to 30 years.
When supply is disrupted, he said, semiconductor fabrication facilities will be able to remain operational for six to 18 months. The graphics processing units at the core of AI data centers run continuously and burn out in four to six years.
His advice for the real estate developers, investors, owners and others in the room was not to stop building. “Does that mean I don’t think you should build data centers? Not what I’m saying,” he said. “The ones that we are building now will be the last ones we have for a while. Just if you’re in the real estate world, keep in mind that there is an end date here and get paid up front.”
Where Industrial Growth Could Happen
Asked which areas stand to benefit most from a return to manufacturing, Zeihan identified three regions:
- The Texas Triangle, which benefits from integration with northern Mexico. However, he noted that power constraints and a shrinking pipeline of new workers will likely limit the explosive growth of recent years.
- The northern half of Auto Alley, particularly Indiana, Ohio and Michigan, where existing industrial plant and skilled workers could support retooling – though he said this depends in part on continued integration with Canada.
- Northern Appalachia, where existing high-capacity transmission allows power plants to serve facilities in other states. Combined with the Ohio River and a large blue collar workforce, “the three things that you need are right there,” he said. “But policy has to shift to bring them together.”
Zeihan expects state and local governments to play a larger role in industrial development in the coming years. “It really is up to state and local governments to step in and find a way to make things happen,” he said.
This post is brought to you by JLL, the social media and conference blog sponsor of the CREDA Conference 2026. Learn more about JLL at www.us.jll.com or www.jll.ca.